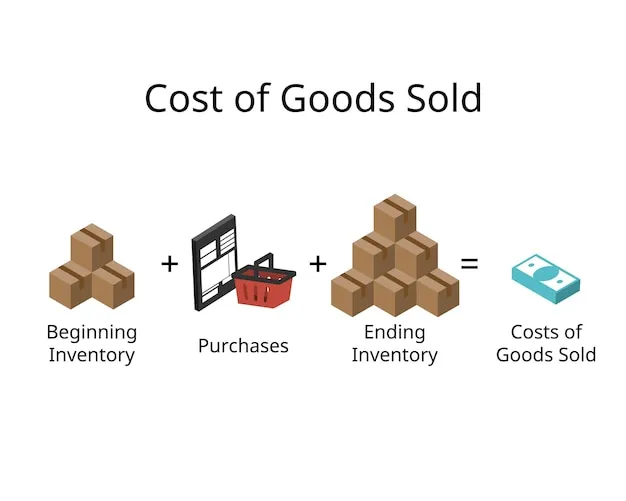
Cost of Goods Sold (COGS): Formula, Examples and What to Include
The COGS formula with what goes into cost settled line by line from IFRS for SMEs, worked for a Lusaka shop in kwacha and a Kampala candle maker three ways.
The EOQ formula worked for a Kampala hardware shop in Uganda shillings: what goes into each input, why a full lorry costs only 1.4% more than the exact answer, and when a quantity discount beats the formula.
Direct materials, labour and overheads worked through one Kampala school desk in UGX, why a slow month must not raise the cost of each unit, and two savings worth UGX 15.8 million a year.
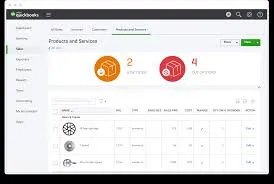
Which QuickBooks plans track stock, the costing choice you can't undo (worked in Uganda shillings), what QuickBooks Online leaves out, and how to use it beside a till.
What changes in stock control when a shop opens its second branch: how much stock to send, why the quieter branch can need the higher reorder level, and how to count with goods on the road.
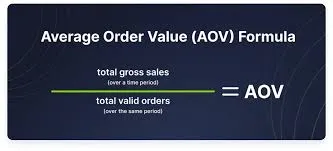
Work out average order value from a till in rand, see why the mean misleads when traders buy in bulk, and test whether a minimum-spend offer pays before you run it.
What counts as a raw material under IFRS, how to value it, and every formula worked through one month of a Nairobi soap maker's imported caustic soda, with the reorder point a six-week lead time needs.
Staff won't log every cup and till roll, so count instead. A weekly count sheet, reorder levels worked from usage, and the cups-against-sales check that finds GHS 1,664 a year.
How to build SKU codes that stay readable, when the maker's barcode should be your code, and what one lookalike mix-up costs at the till and at the count.
Which code goes on raw materials, cartons and finished packs, where to scan, and why a batch code on every carton turns a UGX 86.4 million recall into UGX 14.4 million.
A distributor sells to shops across a region, a dealer to the people who use the product. The margins worked for a Kampala maker, the law on resale prices, and the contract points.
The one full count your accounts depend on: what to include, where to draw the cut-off, how to value what you count, and how a UGX 3 million mistake moves profit and tax.